>
 TaxCalc.pk
FY 2026-27
Understand trademark opposition in Pakistan: filing Form TM-5 notices, Form TM-6 counter-statements, statutory 2-month deadlines, evidence affidavits, and heari
By Syed Asad Hussain Zaidi · 8 September 2026
Author Note / Last Updated: Updated for 2026–27 by Syed Asad Hussain Zaidi | Advocate High Court | Senior IP Litigation Counsel
Passing substantive examination before an examiner at the Trade Marks Registry (TMR) of IPO-Pakistan does not conclude the registration process. Under the Trade Marks Ordinance, 2001 and the Trade Marks Rules, 2004, every accepted application is published in the official monthly Trade Marks Journal for public scrutiny.
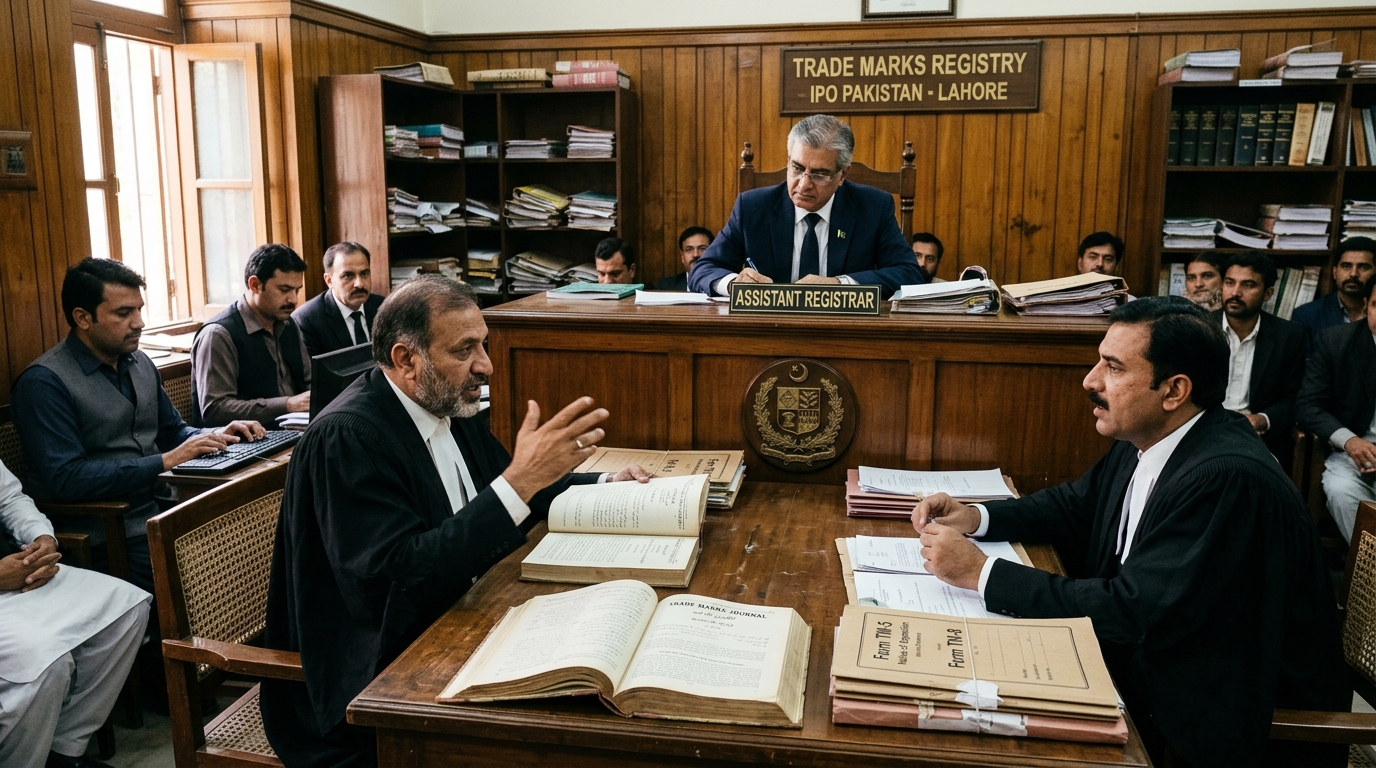
Publication triggers a statutory two-month opposition window. During this period, any person or enterprise possessing legitimate legal interest may challenge the application under Section 28 by filing a formal Notice of Opposition on Form TM-5. The applicant must then defend their mark by submitting a Counter-Statement on Form TM-6.
(Procedural Note on Forms: Form TM-5 and Form TM-6 are the statutory instruments for ordinary trademark opposition proceedings. Forms TM-8 and TM-9 are separate, specialized filings prescribed under Rules 113 and 120 specifically for collective marks and certification trade marks).
This guide provides the full legal procedure, deadlines, evidence requirements, and hearing stages of trademark opposition in Pakistan.
The opposition procedure is governed by Section 28 of the Trade Marks Ordinance, 2001, read alongside Rules 30 through 43 of the Trade Marks Rules, 2004:
| Stage | Action / Statutory Step | Relevant Form & Rule | Timeframe / Deadline | | :--- | :--- | :--- | :--- | | Stage 1 | Journal Publication | Published in monthly Trade Marks Journal | Day 0 (Commencement of opposition window) | | Stage 2 | Notice of Opposition | Form TM-5 (Section 28(1), Rule 30) | Within 2 months of Journal publication | | Stage 3 | Service of Notice | TMR formally transmits notice copy to applicant | Registry processing | | Stage 4 | Filing Counter-Statement | Form TM-6 (Section 28(3), Rule 31) | Within 2 months of receiving TM-5 copy | | Stage 5 | Opponent's Evidence | Evidence by Affidavit (Rule 32) | Within 2 months of receiving TM-6 copy | | Stage 6 | Applicant's Evidence | Evidence by Affidavit (Rule 33) | Within 2 months of receiving opponent's affidavit | | Stage 7 | Opponent's Evidence in Reply | Rebuttal Affidavit (Rule 34) | Within 1 month of receiving applicant's affidavit | | Stage 8 | Oral Hearing & Final Order | Arguments before Registrar (Rule 37) | Hearing notice issued; final decision by Registrar |
Where no opposition is filed within the statutory two-month window (or any extension granted), the application proceeds to registration upon payment of the registration fee (Form TM-11).
An opponent must establish recognized statutory grounds under the Trade Marks Ordinance, 2001:
Most oppositions arise under Section 17, where an existing rightsholder claims priority:
An opponent may also argue inherent legal defects:
If you are an applicant facing opposition, filing a timely Counter-Statement is mandatory:
Opposition proceedings mirror civil trials, conducted through written affidavits:
Yes. An opponent may apply for an extension of time by filing Form TM-56 prior to the expiry of the initial two-month period, citing valid reasons such as ongoing settlement discussions or awaiting foreign powers of attorney.
Form TM-6 is the standard counter-statement in opposition to an ordinary trademark application. Form TM-8 is a counter-statement used exclusively in proceedings involving collective marks or certification trade marks under Rules 113 and 120 of the Trade Marks Rules, 2004.
Legal & Statutory Notice: The information provided in this publication is for general educational, academic, and statutory informational purposes only under the relevant laws of Pakistan (including the Income Tax Ordinance, 2001, the Companies Act, 2017, and the Trade Marks Ordinance, 2001). This content does not constitute formal legal, financial, or tax advice. For specific assessments, consult a licensed Advocate or qualified tax professional.