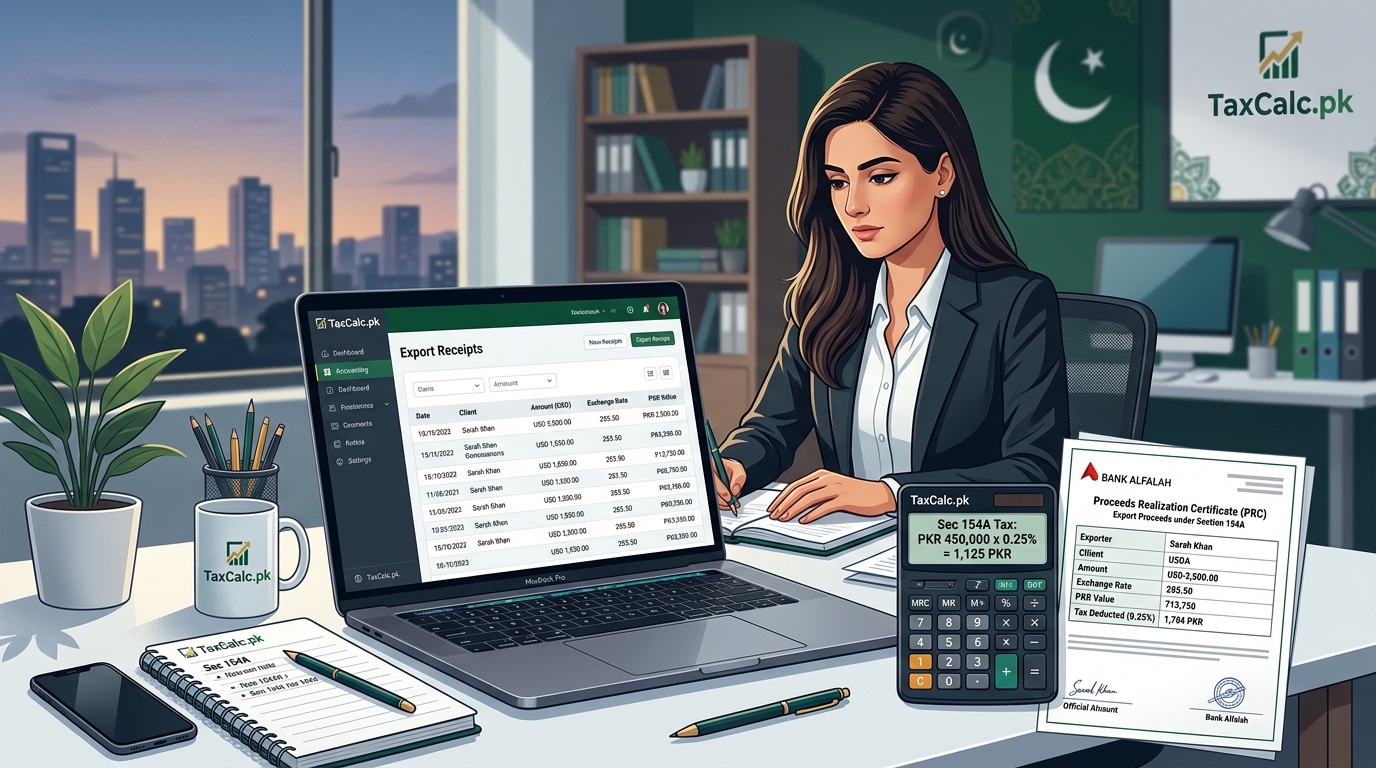
>
 TaxCalc.pkFY 2026-27
Complete legal guide to freelancer tax in Pakistan under Section 154A: 0.25% PSEB concession, 1% default rate, PRC compliance, and Iris 2.0 filing rules.
By Syed Asad Hussain Zaidi · 29 September 2026
✓ Verified for Tax Year 2026-27 (Finance Act 2026) · High Court Advocate Review
Calculate 0.25% vs 1% final tax regime, PSEB registration savings, and PRC compliance for IT exports.
Author Note / Last Updated: Updated September 2026 by Syed Asad Hussain Zaidi | Advocate High Court & Professional Tax Consultant. Reviewed by Syed Asad Hussain Zaidi, Advocate High Court & Tax Consultant.
Pakistan’s digital services sector has expanded rapidly, making foreign remittances from independent freelancers, software consultants, and digital agencies one of the most critical sources of foreign currency in the national economy. To accelerate this growth while bringing foreign receipts into the documented banking system, the Government of Pakistan instituted a specialized concessionary tax regime under Section 154A of the Income Tax Ordinance, 2001.
Under this statutory framework, qualifying exports of computer software, IT services, and IT-enabled services (ITES) are subject to a 0.25% withholding tax rate if registered with the Pakistan Software Export Board (PSEB). For other qualifying service exporters or those without active PSEB credentials, a 1% withholding tax rate applies.
Crucially, the Federal Board of Revenue (FBR) withholding tax card extends this concessionary regime through tax year 2029. However, securing this deduction as a final tax discharge requires strict procedural compliance. Without proper banking documentation, timely return filing, and active registration, freelance remittances risk forfeiture of the concession and reclassification under standard progressive business income tax rates reaching up to 35% or 45%.
This guide breaks down every statutory requirement, procedural protocol, and filing step under Section 154A so you can legally preserve your export income and maintain bulletproof compliance with the FBR.
The primary rate schedule and statutory authority for export tax on services are codified in Section 154A and Division IVA, Part III of the First Schedule to the Income Tax Ordinance, 2001:
| Regime | Tax Rate | Covered Service Categories | Key Compliance Mandates | | :--- | :--- | :--- | :--- | | Concessionary IT Export | 0.25% Final Tax | Computer software development, SaaS, IT-enabled services (ITES), call center operations, BPO. | Active PSEB registration certificate, SBP IT purpose codes (9181-9184), timely return & wealth filing. | | Standard Services Export | 1.00% Default Rate | Non-IT technical, advisory, consulting, and engineering services exported abroad; or IT exports lacking active PSEB registration. | Timely annual return and wealth reconciliation; settlement via banking channels. |
[!IMPORTANT]
Cumulative Statutory Conditions for Section 154A Final Tax Regime:
1. Timely filing of annual Income Tax Return under Section 114.
2. Complete wealth statement reconciliation under Section 116.
3. Provincial sales tax compliance with relevant authority (PRA, SRB, KPRA, or BRA).
4. Timely submission of withholding tax statements under Section 165 (if employing personnel).
5. Realization of proceeds exclusively through formal banking channels supported by SBP PRCs.
The law establishes clear criteria distinguishing the two withholding rates:
If statutory filing conditions are not met, the withholding does not constitute final tax, exposing the gross receipts to audit and progressive normal taxation.
A common misconception among online professionals is that simply calling yourself a "freelancer" or earning foreign currency on Upwork, Fiverr, or Deel automatically secures the 0.25% rate. The statute does not recognize informal labels. Eligibility is determined strictly by the nature of the service and regulatory registration.
Under the PSEB framework and Section 154A definitions, eligible export streams include:
Services that do not fall under IT or ITES definitions—such as legal consulting, physical architectural project oversight, commodity brokerage, or commission agency work—do not qualify for the 0.25% PSEB rate. They default to the 1% general service export deduction or standard business income.
To ensure that the 0.25% (or 1%) tax withheld at the bank represents your final and absolute tax discharge, Section 154A(2) mandates that the taxpayer satisfy five cumulative conditions:
| Statutory Condition | Legal Provision | Operational Action Required | | :--- | :--- | :--- | | 1. Annual Income Tax Return | Section 114 | Must file the annual income tax return on FBR Iris 2.0 on or before the statutory deadline (September 30). | | 2. Annual Wealth Statement | Section 116 | Must file an exact reconciliation of assets, liabilities, and net foreign remittances realized during the tax year. | | 3. Provincial Sales Tax Return | PRA / SRB / KPRA / BRA | Must register with the provincial sales tax authority and file periodic (usually "Nil" or exempt) sales tax returns. | | 4. Withholding Tax Statements | Section 165 | If you employ staff or sub-contractors and deduct withholding tax, statutory statements must be submitted. | | 5. Banking Channel & PRC | SBP Regulations | Funds must clear through authorized banking dealers and be certified with a Proceeds Realization Certificate (PRC). |
Critical Warning: If an IT exporter fails to file the annual return by the due date, the final tax status is legally voided. The FBR may treat the foreign income under normal business tax slabs, issuing demand notices under Section 122 for assessment at rates up to 35% for individuals or 29% for corporate entities.
To understand the immense financial advantage of maintaining full compliance under Section 154A, consider the annual tax liabilities for a Pakistani freelancer earning foreign currency across different revenue tiers (assumed exchange rate: 1 USD = 280 PKR):
| Monthly Revenue (USD) | Annual Gross (PKR) | Section 154A PSEB Rate (0.25%) | Section 154A Default Rate (1.00%) | Unregistered / Non-Compliant Slab Rate (Up to 35%) | | :--- | :--- | :--- | :--- | :--- | | $1,000 / mo | PKR 3,360,000 | PKR 8,400 | PKR 33,600 | PKR 427,000 | | $2,500 / mo | PKR 8,400,000 | PKR 21,000 | PKR 84,000 | PKR 2,175,000 | | $5,000 / mo | PKR 16,800,000 | PKR 42,000 | PKR 168,000 | PKR 5,115,000 | | $10,000 / mo | PKR 33,600,000 | PKR 84,000 | PKR 336,000 | PKR 10,995,000 |
PKR 7,000,000 × 0.0025 = PKR 17,500.PKR 7,000,000 × 0.01 = PKR 70,000.PKR 1,685,000.You can run your exact customized numbers on the interactive TaxCalc.pk Freelancer Tax Calculator.
Securing and protecting the 0.25% rate requires coordination across four regulatory touchpoints: the FBR, the PSEB, your commercial bank, and provincial tax revenue boards.
| Step | Phase | Action Required | Statutory Objective | | :--- | :--- | :--- | :--- | | 1 | Tax Registration | Obtain National Tax Number (NTN) on FBR Iris. | Establishes formal tax identity on Active Taxpayer List (ATL). | | 2 | Sector Accreditation | Register on PSEB Portal as Individual Freelancer or IT Company. | Secures mandatory eligibility certificate under Section 154A. | | 3 | Banking Setup | Open dedicated Exporter Bank Account with SBP IT Purpose Code. | Directs inward remittances under correct FX classification. | | 4 | Documentation | Obtain Proceeds Realization Certificates (PRCs) for all receipts. | Evidences formal foreign currency banking realization. | | 5 | Return Submission | File annual Form 114(1) under Final/Fixed Tax tab in Iris before deadline. | Formally discharges annual tax liability at concessionary rate. |
pseb.org.pk) and select Freelancer Registration.Every time a foreign wire transfer or platform withdrawal (from Payoneer, Wise, Stripe, or direct SWIFT) is credited to your Pakistani account:
When filing your annual return:
Even experienced freelancers frequently fall into administrative traps that jeopardize their final tax status. The FBR’s automated audit engine actively flags these discrepancies:
Bypassing commercial banks by using peer-to-peer (P2P) crypto transfers, hawala, or unofficial currency exchangers to avoid Payoneer or wire fees is hazardous. If money arrives as a domestic inter-bank fund transfer (IBFT) from an unrelated third party inside Pakistan:
Because Section 154A is an FTR regime, the 0.25% tax is calculated on gross receipts, not net profit. You cannot claim deductions for office rent, internet costs, laptop depreciation, or utility bills. In exchange for forfeiting expense deductions, the government grants you an ultra-low tax rate on your entire turnover.
PSEB registration certificates are valid for one calendar or financial year. If your certificate expires on December 31 and you receive export remittances in March before renewing, your bank is legally required to deduct the default 1% rate. The excess 0.75% is difficult to reclaim from the FBR once deducted.
While IT exports are generally zero-rated or exempt from provincial sales taxes under Punjab Revenue Authority (PRA), Sindh Revenue Board (SRB), or Khyber Pakhtunkhwa Revenue Authority (KPRA) legislation, registration is nonetheless mandatory. Failure to register and submit periodic "Nil" returns can result in suspension of your NTN or issuance of compliance show-cause notices.
Yes. If you held a valid PSEB certificate at the time of remittance but the bank deducted 1% due to administrative delay, you can reflect the actual deducted tax against your 0.25% liability when filing on Iris 2.0. The excess 0.75% appears as a refundable credit. However, obtaining a physical cash refund from the FBR involves substantial procedural delays, making proactive bank notification essential.
No. Section 154A strictly applies to the export of services, meaning the service must be rendered from Pakistan to a recipient located outside Pakistan and paid for in convertible foreign exchange. Local freelance services billed to Pakistani companies fall under standard domestic withholding rules (Section 153) and normal business income slabs.
The 0.25% withholding applies to the net amount remitted into your Pakistani bank account as documented on your PRC. If Upwork deducts 10% platform fees abroad and your bank receives $900 from an original $1,000 contract, the bank applies 0.25% on the PKR equivalent of $900.
If you receive an audit notice, immediately compile your Documentary Compliance File:
When these records match your Iris 2.0 return line-for-line, the FBR assessing officer is legally bound to accept your Section 154A return and close the inquiry.
| Checklist Item | Current Status | Recommended Action | | :--- | :--- | :--- | | FBR NTN & Business Profile | Verified on Iris 2.0 | Ensure "IT Services" is listed under Form 181. | | PSEB Freelancer Registration | Active for Tax Year | Renew annually via pseb.org.pk. | | Bank Purpose Code | Code 9182 / 9181 | Confirm with bank foreign exchange department. | | Proceeds Realization Certificates | Digitally Archived | Match each invoice with its corresponding PRC. | | Iris Return Filing | Form 114(1) FTR Tab | File under Section 154A before September 30. |
For precise bracket analysis, salary deductions, and corporate structuring options, explore our comprehensive suite of calculators and legal services:
Disclaimer: Tax legislation and circulars in Pakistan are subject to ongoing amendments by the Federal Board of Revenue and provincial legislatures. This guide provides legal and procedural analysis for Tax Year 2026 and 2027 based on the Income Tax Ordinance, 2001 and Finance Act statutory schedules. It does not constitute individual attorney-client legal counsel. For complex corporate structuring or contested audit proceedings, consult a qualified tax advocate.
Legal & Statutory Notice: The information provided in this publication is for general educational, academic, and statutory informational purposes only under the relevant laws of Pakistan (including the Income Tax Ordinance, 2001, the Companies Act, 2017, and the Trade Marks Ordinance, 2001). This content does not constitute formal legal, financial, or tax advice. For specific assessments, consult a licensed Advocate or qualified tax professional.